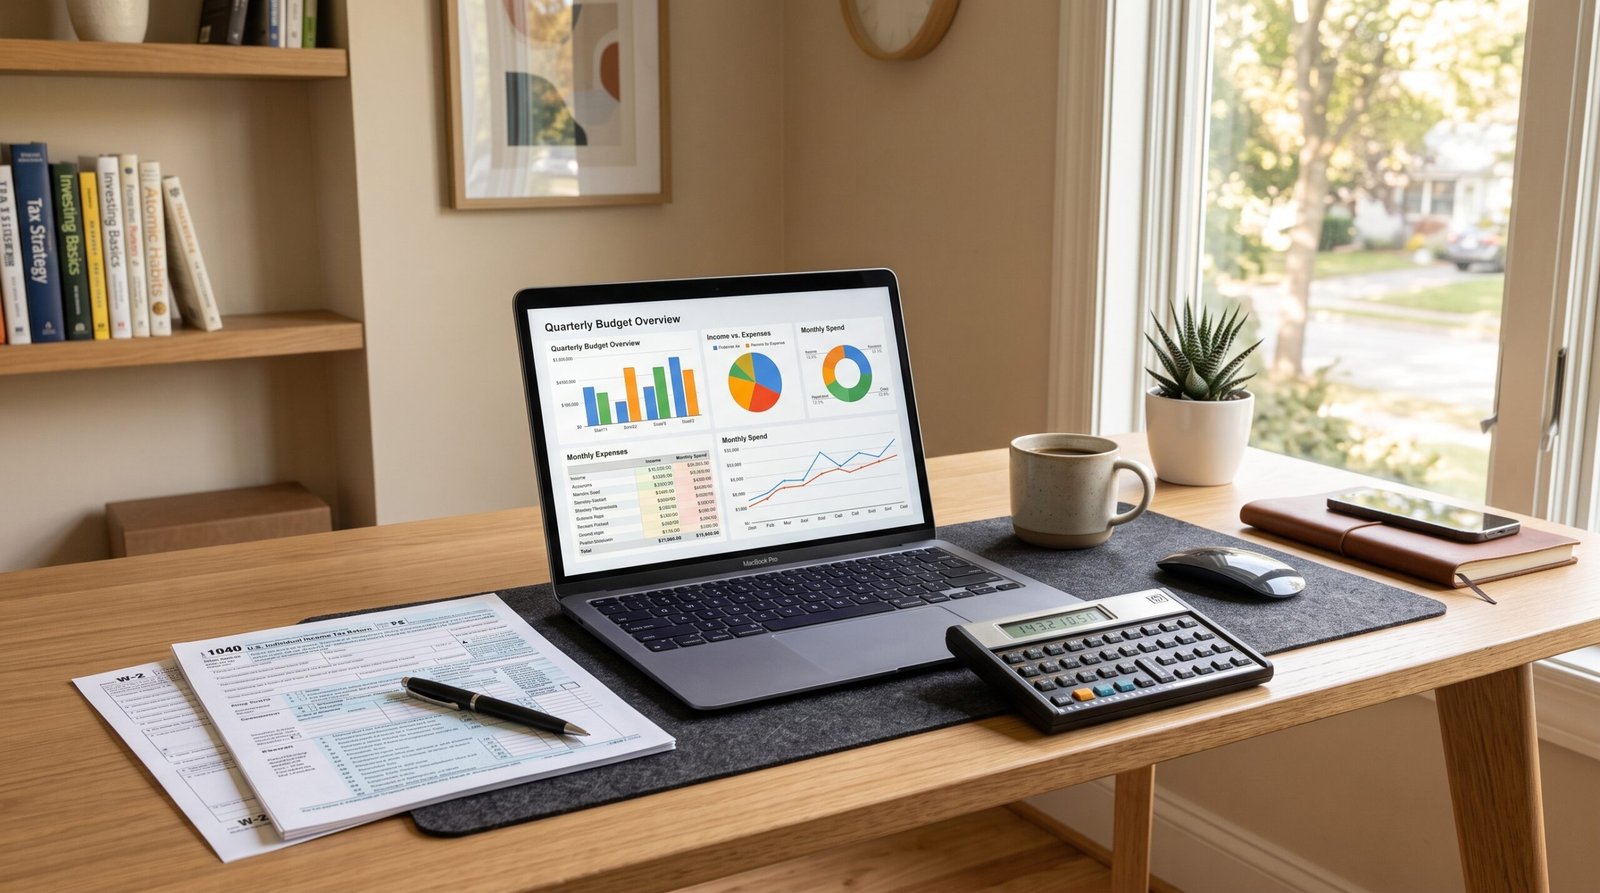
Let us be completely honest. Paying for professional inhome childcare is one of the largest line items in any family budget. When you factor in competitive hourly wages, benefits and payroll administration the numbers add up fast.
Fortunately you do not have to shoulder the entire financial burden alone.
By taking advantage of federal tax credits, dependent care accounts and legal structuring you can recover a significant portion of your childcare expenses. Understanding the childcare tax credit is a game changer for modern families. In 2026 tax codes offer tangible incentives for compliant household employers. In this guide we will walk through how to claim valuable tax breaks, utilize flexible spending accounts and maximize your household savings.
The Power of the Child and Dependent Care Tax Credit
The federal government offers a specialized tax credit designed to help working families offset the cost of caregiving services including nannies and in-home specialists.
Unlike a tax deduction which simply lowers your taxable income, a tax credit directly reduces your actual tax liability dollar for dollar. To qualify for this credit you must earn income, pay a compliant wage to a verified caregiver and file your taxes correctly using official guidance from the Internal Revenue Service.
Making sure your caregiver is classified correctly as a W-2 employee is mandatory if you want to claim these credits safely without triggering audits. Review our breakdown on nanny overtime laws and tax compliance.
Leveraging a Dependent Care Flexible Spending Account
Another fantastic financial tool is a Dependent Care Flexible Spending Account (FSA) typically offered through your corporate employer benefits package.
A dependent care FSA allows you to set aside pre-tax dollars straight from your paycheck to pay for eligible childcare expenses like your nanny’s weekly wages. Because those funds are deducted before federal income taxes are calculated your overall taxable income drops substantially.
When you are evaluating whether an in-home nanny fits your budget better than group facilities, compare total costs using insights from our guide on nanny cost vs daycare cost.
Why Legal Tax Compliance Saves You Money
Some parents are tempted by informal under-the-table cash arrangements thinking they will save money by avoiding taxes.
In reality paying cash cuts you off entirely from claiming childcare tax credits and FSA reimbursements. Operating above board not only keeps your household legally protected under guidelines from the U.S. Department of Labor but also allows you to claw back thousands of dollars in tax savings annually.
Frequently Asked Questions
Generally no. The IRS prohibits claiming tax credits for payments made to your own dependents or the child’s parents.
Contribution limits are adjusted periodically by federal tax authorities so always check current IRS contribution caps during your annual open enrollment window.
Yes. You will need your caregiver’s Social Security number or Employer Identification Number (EIN) when filing your annual tax return.
Yes you can use both, but any dollars contributed through a pre-tax FSA reduce the remaining expense pool eligible for the tax credit dollar for dollar.
Conclusion
Maximizing tax credits and employer savings turns high childcare expenses into manageable household investments. When you want guidance on structuring fair employment agreements or finding elite childcare professionals for your family, you can easily connect with our team directly through our contact page to begin your journey with Inhome Care Solutions.